
State Bank keeps policy rate unchanged at 11.5%

The State Bank of Pakistan on Monday kept the policy rate unchanged at 11.5 percent as rising global commodity prices and heightened geopolitical risks offset signs of a gradual recovery in domestic economic activity.
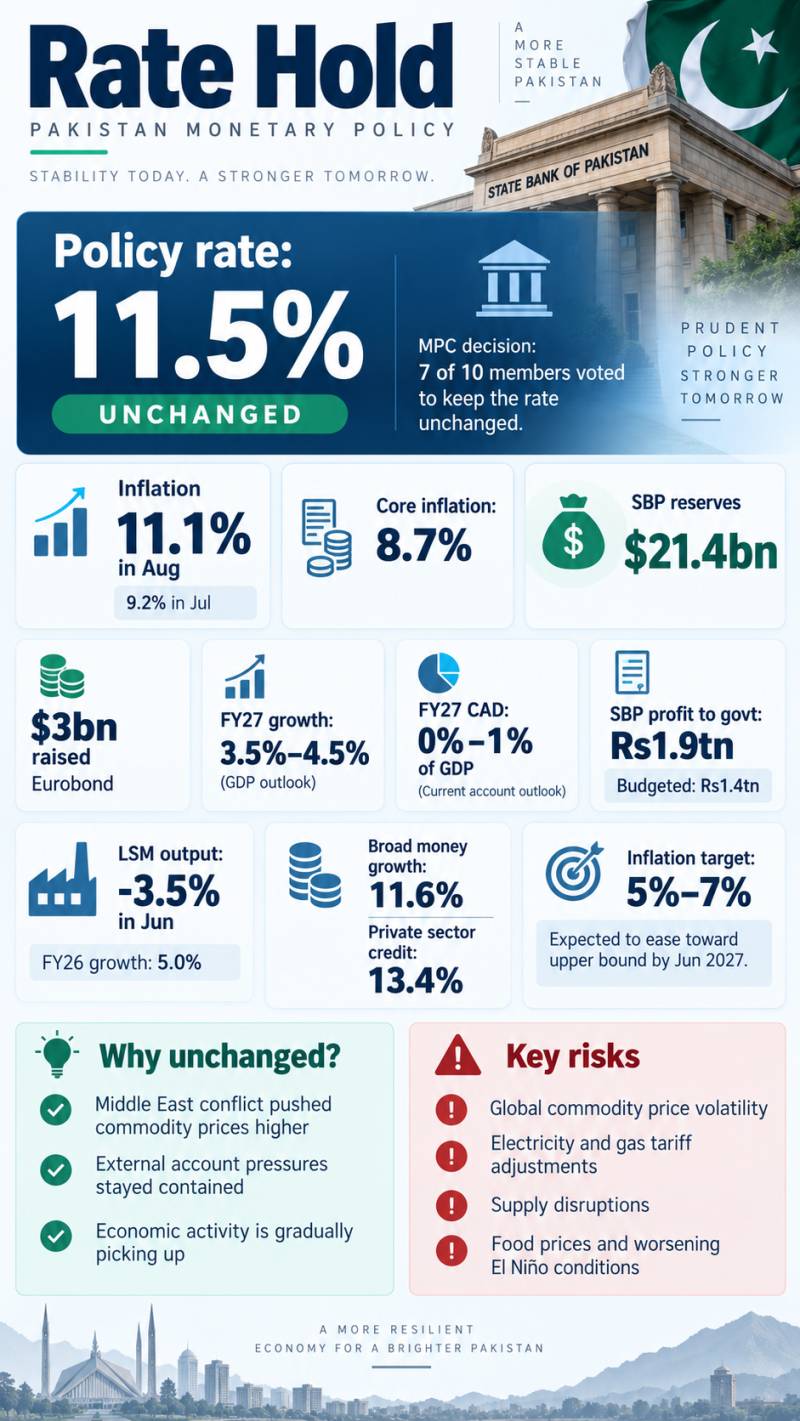
The Monetary Policy Committee (MPC) took the decision by a majority of seven out of 10 members at its meeting on September 14.
The committee said the prolonged Middle East conflict had intensified, pushing already elevated global commodity prices higher and prolonging supply chain disruptions.
However, recent domestic macroeconomic data remained broadly in line with the MPC's expectations.
Headline inflation rose to 11.1 percent year-on-year in August from 9.2 percent in July, while core inflation remained slightly below expectations.
The MPC said external account pressures remained contained due to robust workers' remittances and higher financial inflows.
Economic activity, which slowed during the fourth quarter of FY26, has also started to recover gradually, according to recent high-frequency indicators.
The committee said the current monetary policy stance remained appropriate to steer inflation towards the medium-term target range of 5-7 percent.
However, it warned that uncertainty surrounding the economic outlook had increased, particularly because of the worsening geopolitical environment.
The MPC noted that Moody's had upgraded Pakistan's sovereign credit rating to B3 with a stable outlook.
Pakistan also raised $3 billion through Eurobonds in international capital markets. The bond issuance, along with continued foreign exchange purchases by the SBP, helped push the central bank's foreign exchange reserves above $21 billion.
The SBP said its FX reserves had reached $21.4 billion.
The central bank said inflation expectations among businesses and consumers increased in September while confidence weakened.
Large-scale manufacturing output declined by 3.5 percent in June, though cumulative LSM growth for FY26 stood at 5 percent.
The MPC said fiscal consolidation during FY26 exceeded the government's budgetary target, mainly due to contained current expenditure and lower interest payments.
Federal Board of Revenue tax collection remained on target during July-August FY27, although its growth slowed compared with last year.
The SBP also transferred Rs1.9 trillion in profits to the government, significantly higher than the budgeted Rs1.4 trillion.
The committee said central banks around the world had become more cautious amid challenging global economic conditions.
GDP growth seen at 3.5-4.5%
The SBP maintained its projection for Pakistan's real GDP growth at 3.5 to 4.5 percent during FY27.
It said economic activity appeared to be gradually recovering after slowing during the fourth quarter of FY26 because of conflict-related disruptions.
High-frequency indicators, including petroleum product sales, private sector credit, textile exports, business sentiment and satellite data on nighttime lights and gas emissions, pointed towards a recovery in July.
The central bank said increased acreage under rice and sugarcane crops and encouraging early reports on cotton arrivals had also improved the outlook for agriculture.
It said improvement in commodity-producing sectors would also support growth in the services sector.
Current account deficit seen at up to 1% of GDP
The SBP said the current account deficit in July remained largely in line with expectations as growth in imports of goods and services outpaced increases in exports and workers' remittances.
It expects resilient remittances and higher information and communications technology exports to keep the FY27 current account deficit between zero and 1 percent of GDP.
The central bank said planned financial inflows and continued FX purchases should meet external financing requirements and support foreign exchange reserves.
It expects reserves to approach three months of import cover by the end of June 2027.
However, the SBP warned that elevated global commodity prices and supply constraints linked to developments in the Middle East posed risks to the external outlook.
SBP calls for faster fiscal reforms
The MPC said Pakistan achieved stronger-than-budgeted fiscal consolidation during FY26.
It urged the government to sustain efforts to meet its tax revenue target amid uncertain domestic and global conditions.
The committee called for faster fiscal reforms, particularly measures to broaden the tax base and reduce losses of public sector enterprises.
It said those reforms were necessary to support higher and sustainable economic growth.
Private sector credit rises 13.4%
Broad money growth slowed to 11.6 percent year-on-year as of August 28 from 13.2 percent at the time of the previous MPC meeting.
The SBP attributed the slowdown to lower contributions from both net domestic assets and net foreign assets of the banking system.
Private sector credit, meanwhile, increased by 13.4 percent year-on-year amid lower government borrowing from banks and recovering economic activity.
Credit growth was broad-based across working capital, fixed investment and consumer financing.
Wholesale and retail trade, agriculture and the sugar sector remained among the major borrowers.
The central bank expects private sector credit growth to strengthen further as economic activity improves.
Inflation rises to 11.1%
Headline inflation increased from 9.2 percent in July to 11.1 percent in August.
The SBP said higher food prices, particularly wheat and related products and perishable items, remained a major driver of inflation.
The intensifying Middle East conflict also kept energy inflation elevated.
Higher fuel prices pushed up transportation costs and contributed to core inflation reaching 8.7 percent.
Consumer and business inflation expectations also increased in the latest surveys.
However, the MPC said changes in the high-speed diesel pricing mechanism caused a sharp decline in diesel prices in August, partly offsetting the impact of higher international prices.
The committee said positive real interest rates on a forward-looking basis should help contain demand pressures and limit second-round effects from food and energy inflation.
The SBP kept its overall FY27 inflation outlook broadly unchanged and expects inflation to gradually decline towards the upper end of its 5-7 percent target range by June 2027.
It nevertheless warned that risks to the inflation outlook had increased significantly.
The central bank identified volatility in global commodity prices, changes in electricity and gas tariffs, supply disruptions and unexpected movements in food prices amid worsening El Niño conditions as major risks.
The MPC reiterated that it would closely monitor incoming economic data and developments in the Middle East.
It also called for a prudent mix of monetary and fiscal policies, stronger economic buffers and timely structural reforms to absorb future supply shocks, improve productivity and support sustainable economic growth.