
FBR unveils faceless tax regime with algorithm-based audit and assessment
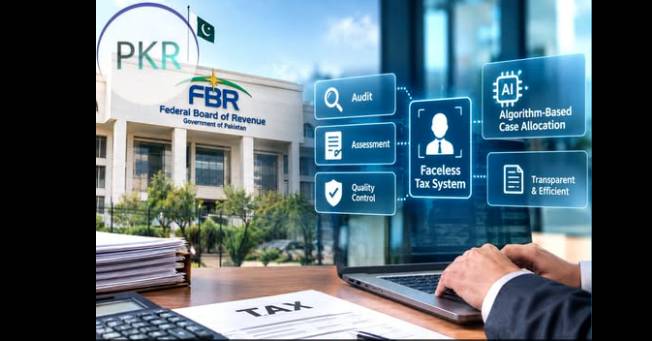

The Federal Board of Revenue (FBR) has proposed a major restructuring of Pakistan’s income-tax administration by introducing a centralised, technology-driven and officer-segregated system for specified audits and assessments, reported 24NewsHD TV channel on Monday.
The proposed framework would shift taxpayer interaction largely to electronic channels while separating audit, assessment and quality-control functions among different officers or units.
The proposal follows the FBR’s establishment of the National Faceless Centre (NFC) in Islamabad. The FBR said the new centre is intended to change how tax audits and assessments are conducted, with cases selected through a computerised, risk-based system and allocated automatically.
The draft rules are not immediately effective. They would come into force from a date subsequently notified by the FBR, with separate commencement dates possible for different classes of cases or proceedings.
Under the proposed framework, the National Faceless Centre (NFC) would conduct proceedings under Section 122E for taxpayers, income, cases, or classes of cases specifically assigned to it by the FBR.
The Centre would operate through four specialised wings:
The NFC would be headed by a Director General and could include Chief Commissioners, Commissioners, Additional Commissioners, Deputy Commissioners, Assistant Commissioners, and other income-tax authorities and support staff designated by the FBR.
The proposed structure would create a distinction between officers responsible for investigating a case, determining the assessment and undertaking quality control.
A central feature of the proposed system is the use of an allocation algorithm.
Once a case is assigned to the National Faceless Centre, the algorithm would allocate audit, assessment and quality-control functions to separate officers or units.
An officer would not be permitted to perform more than one of these functions in respect of the same case and tax year.
The FBR has separately stated that under the faceless system, one officer would conduct the audit, another would make the assessment and a third would review the work for quality before an order is issued.
The identity of the relevant officer or unit would remain electronically recorded in the FBR system, while disclosure would be subject to restrictions under Section 209B.
The proposed Rule 236 provides for a wide range of proceedings to be conducted through the Centre.
These would include audits under Sections 177 and 214C, as well as proceedings concerning unexplained income, assets and other matters under Section 111.
The framework would also cover assessment, amendment of assessment, best-judgement assessment and provisional assessment under Part II of Chapter X, including proceedings under Sections 120, 121 and 122.
Related proceedings could also be brought within the system, including notices, information gathering, evidence collection, penalties and default surcharge arising from the relevant proceedings.
The FBR’s wider 2026 tax reforms have already provided for a legal framework for faceless audit and assessment and the establishment of the National Faceless Centre.
Reporter: Basim Iftikhar