
FCC declares sales tax on construction services in KP as constitutional
Written judgment clarifies limits on Supreme Court after 27th Amendment: Federal Constitutional Court says provinces retain exclusive authority to tax services
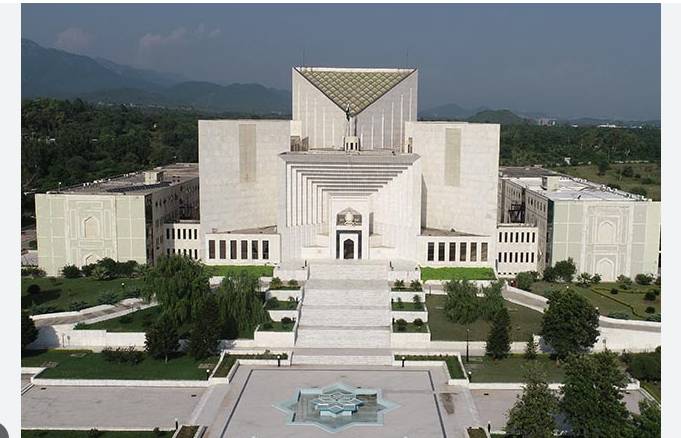

The Federal Constitutional Court has upheld the Khyber Pakhtunkhwa government’s authority to impose sales tax on construction services, dismissing a series of appeals challenging the constitutional validity of the Khyber Pakhtunkhwa Sales Tax on Services Act 2022.
In a written judgment issued on Friday, Justice Aamer Farooq ruled that Serial No. 14 of Schedule II of the Act, which pertains to construction services, does not violate the Constitution. The court held that the provision falls squarely within the taxing powers granted to provinces under the 18th Constitutional Amendment.
According to the 24NewsHD TV channel report, the FCC judgment clarified that, following the 18th Amendment, the authority to levy taxes on services rests exclusively with the provinces, while the federal government retains jurisdiction only over taxation of goods.
The court observed that the impugned provision concerns construction services and does not extend to goods, thereby remaining within the constitutional domain of the provincial legislature.
Addressing broader constitutional questions, the court further ruled that after the 27th Constitutional Amendment, the Supreme Court no longer possesses the authority to strike down laws on constitutional grounds outside the framework prescribed by the amendment.
The judgment stated that constitutional interpretation has been confined to a specific forum established under the amended constitutional scheme.
The court noted that under the 27th Amendment, the Constitutional Court is empowered to call for records from any court or tribunal when adjudicating matters involving constitutional interpretation.
This, the judgment said, reinforces the centralised mechanism introduced by the amendment for resolving constitutional disputes.
While upholding the provincial tax regime, the court emphasised safeguards against double taxation.
It was observed that legal and administrative arrangements exist to ensure that no citizen or company is taxed twice on the same subject.
The bench directed the relevant revenue authority to frame clear rules requiring that a contractor’s total project budget be distinctly apportioned between services and goods, thereby preventing overlapping tax claims.
Reporter: Amanat Gushkuri